Family wealth succession planning
Unsure where to start with wealth succession planning for your family? Our expert wealth planners suggest asking yourself these four important questions.
Quick summary: How family succession planning could help protect your family’s future
Canaccord Wealth’s expert Wealth Planners believe that wealth succession planning should be a key discussion point and incorporated into your financial plans as early as possible. However, it’s true that money can be one of the most awkward topics for many families to discuss. Happily this attitude seems to be changing. The right approach involves asking what is succession planning alongside some other important questions.
• Why should I talk to my family about handing down my wealth?
Talking to your family about handing down wealth helps avoid confusion, reduces tax burden and ensures your wishes are clearly understood and followed.
• When is the best time to transfer my wealth?
The best time to transfer your wealth is either during your lifetime, when it may be more tax-efficient and personally rewarding, or through a regularly updated Will that reflects your goals and legal requirements.
• How much wealth should I pass on?
How much wealth you should pass on depends on your financial situation. Cashflow stress testing can help you gift confidently without risking your future security.
• Who should I pass my wealth on to?
Who you pass your wealth to is personal: family, trusts for grandchildren, or charities. A tailored approach ensures long-term impact and protection.
• How should I exactly transfer my wealth?
You can transfer wealth through lifetime gifts or a Will. Timing, affordability and whether to use trusts will guide the best approach.
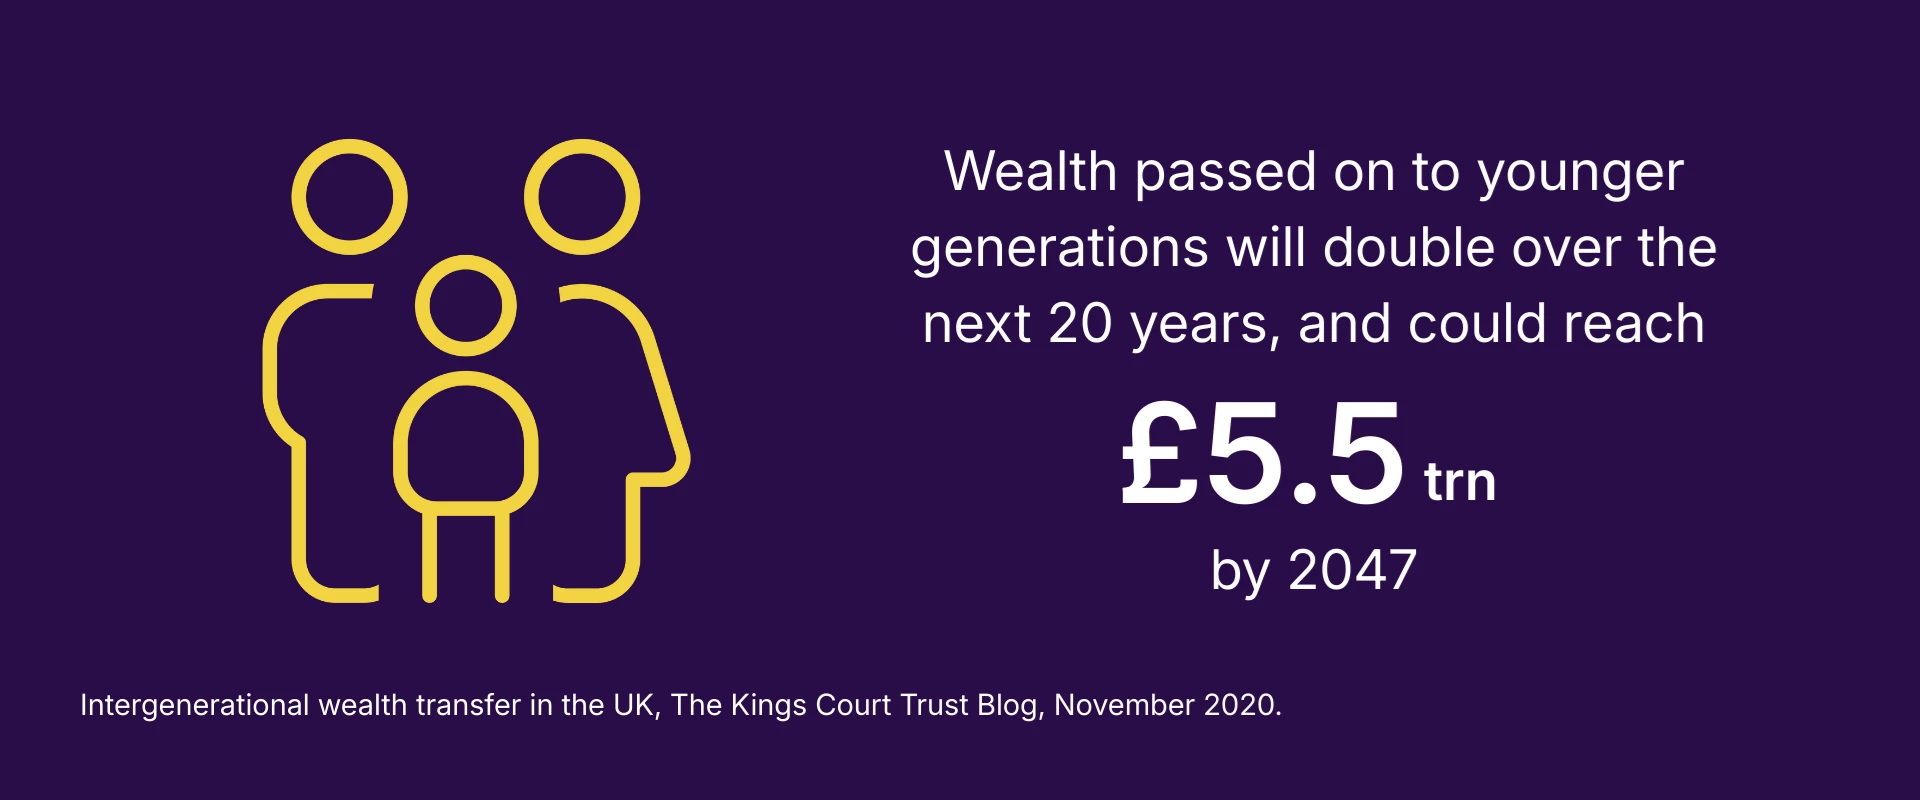
Across the UK, families are working hard to ensure they can leave as much of their estate as possible to their children and grandchildren to ensure their financial stability in the future. In fact, it is believed that the amount of wealth passed on to younger generations could double over the next 20 years, possibly reaching as much as £5.5trn by 2047¹.
Thousands of estates across the UK remain unclaimed. Research published in 2026 identified more than 5,000 unclaimed estates, highlighting the importance of making sure your family knows about your wishes and where important financial information can be found².
However, before you start discussing things with your loved ones, consider these four key questions, all of which are interlinked:
- When do you want to transfer your wealth?
- How much wealth do you want to pass on?
- Who do you want to pass your wealth on to?
- How do you want to transfer your wealth?
Let’s look briefly at each question in turn.
1. When do you want to transfer your wealth?
This isn’t simply a question of leaving money in your Will. There’s other ways of transferring assets during your lifetime, which may have a range of advantages.
Nevertheless, effective wealth succession planning starts with ensuring that your Will is kept up to date, to reflect your personal circumstances and objectives. It should also reflect the latest legal thinking in the jurisdictions where you hold assets.
We suggest that you take professional legal advice, and we generally suggest that you review your Will every two to three years or whenever there is a major change in yours or your family's circumstances – such as marriage, divorce or the birth of a child or grandchild. For example, in England and Wales marriage revokes any existing Will, unless the Will was made in contemplation of the marriage.
We also suggest that you consider linking the value of any legacies to inflation, to ensure they maintain their ‘real’ value.
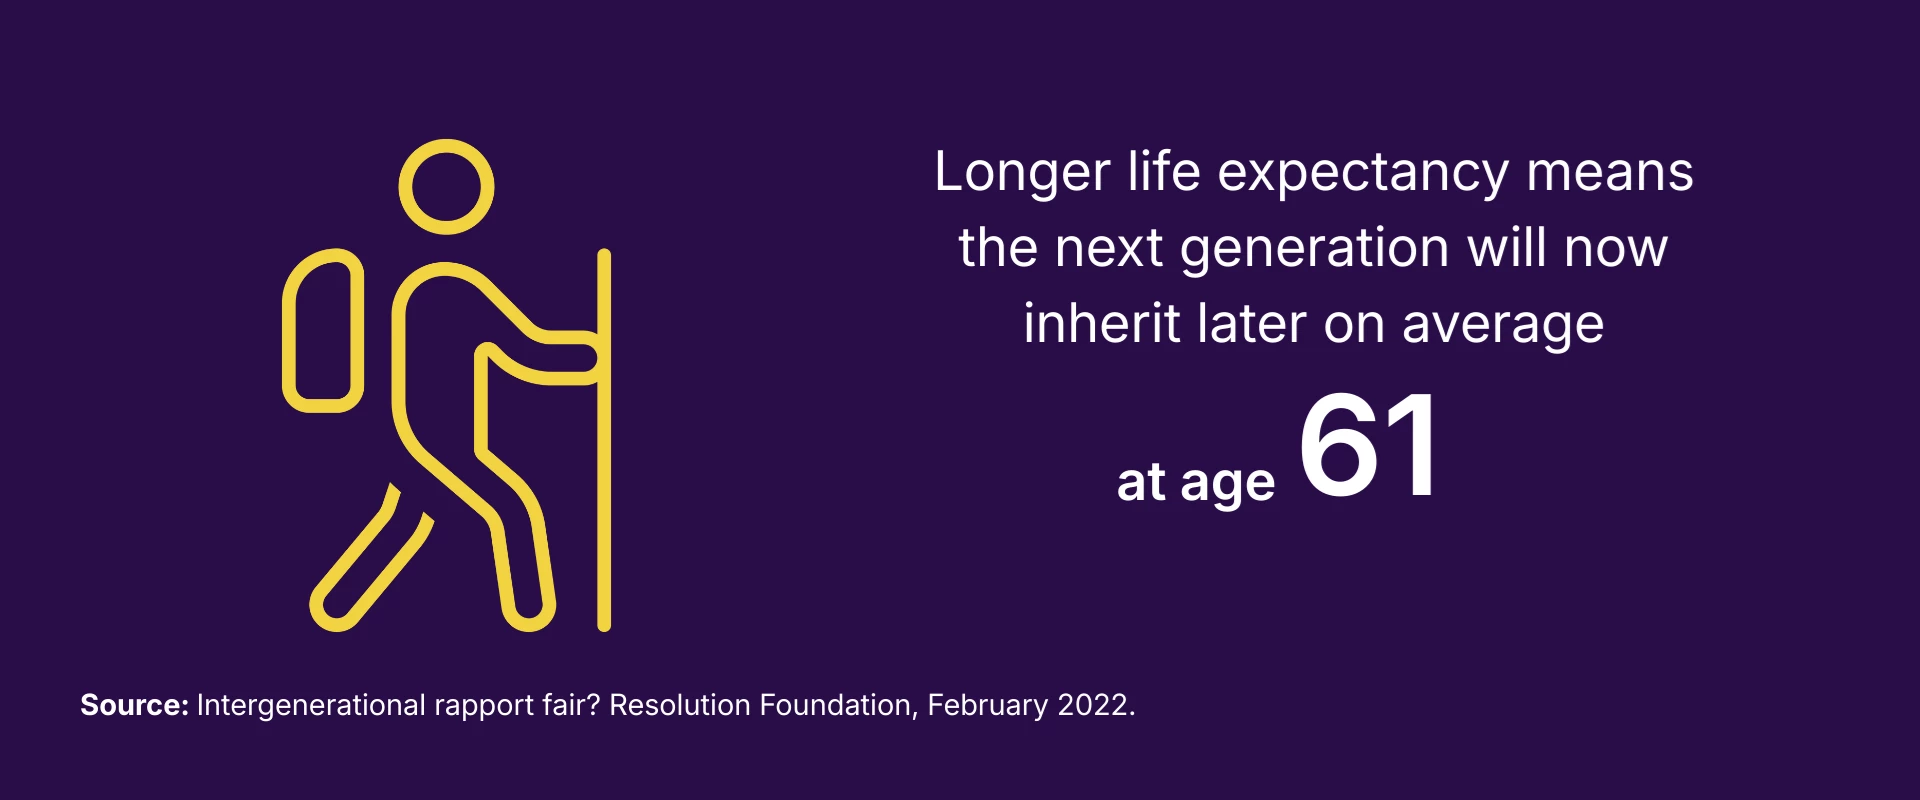
The main advantage of using your Will to transfer wealth is that you won’t compromise your own standard of living. On the other side of the coin, making gifts during your lifetime allows you to experience the joy of seeing your chosen beneficiaries benefiting from your funds. What’s more, if you are exposed to UK taxes, acting sooner rather than later can also be a more tax-efficient way to pass on your wealth to your loved ones.
While everyone’s priorities are different, it’s important to strike the right balance between sharing your wealth with your family and keeping enough to maintain your standard of living and make the most of life now and in the future.
2. How much wealth do you want to pass on?
Where larger gifts are being considered, this cashflow ‘stress testing’ can help you to make informed decisions by showing how much you can afford to give away during your lifetime, within a set range that allows for the worst and best case scenarios. Your circumstances, and those of your family, will change over time, so reviewing your plans regularly can help ensure to reflect your priorities and wishes.
3. Who do you want to pass your wealth on to?
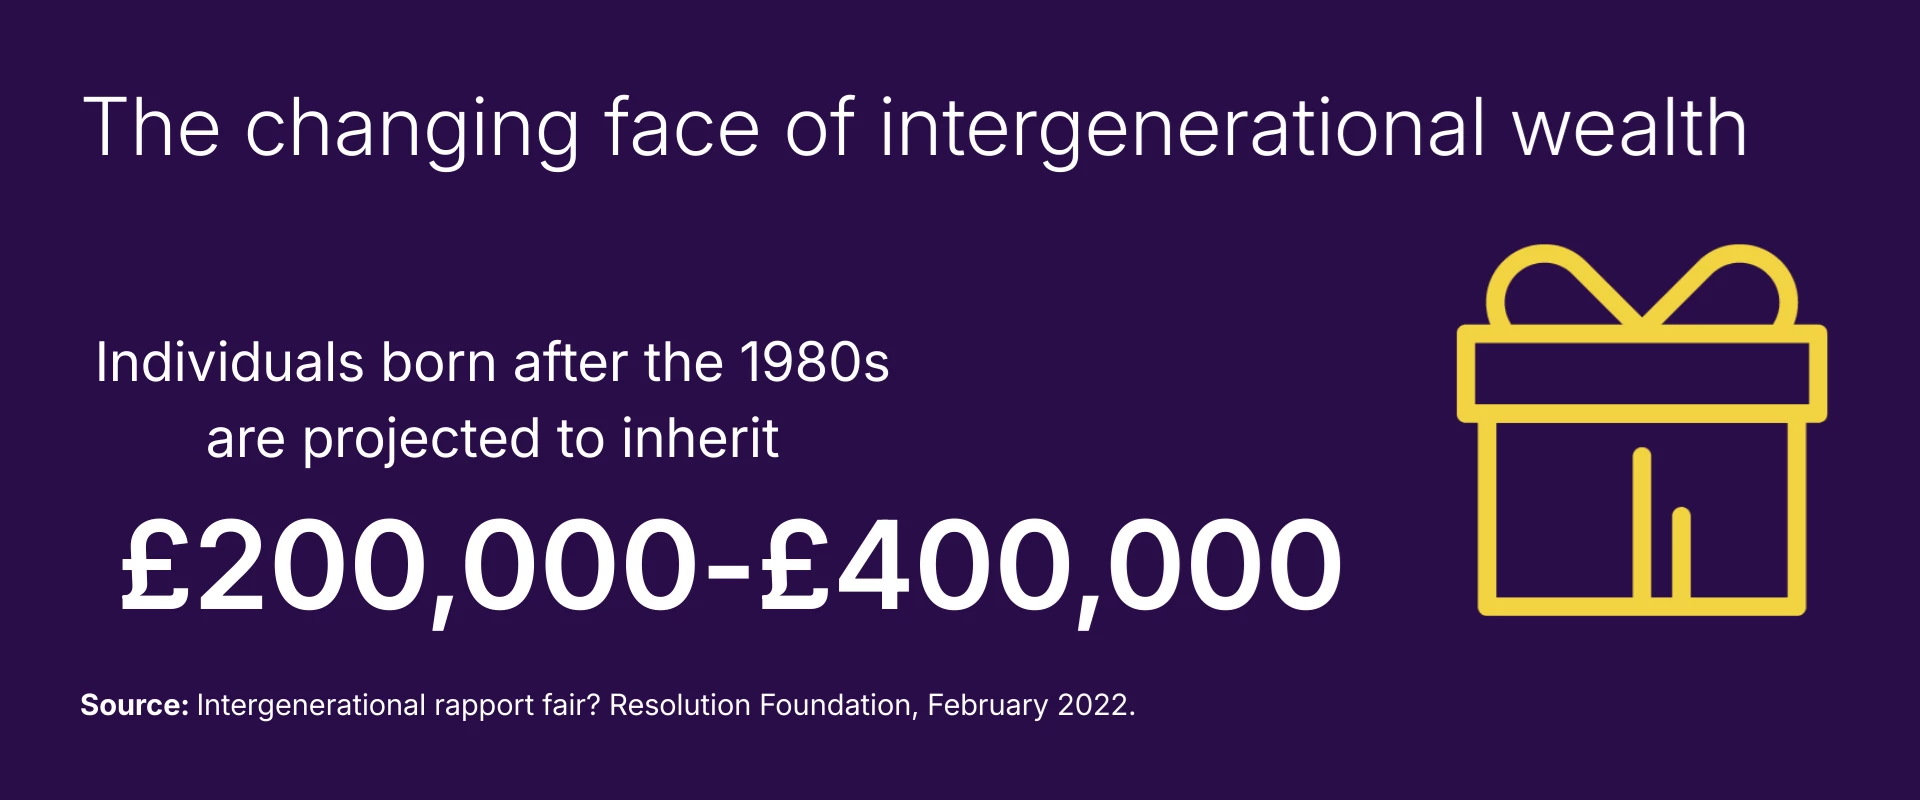
This may be the easiest question to answer and is usually a very personal decision, often linked to the decision about timing. For example, if you have young grandchildren and your main priority is their long-term wellbeing, a trust structure might be an appropriate way forward; this could help with private education costs, university expenses or future property purchases.
Your trustees could have discretion over how much to distribute to the beneficiaries, when and to whom, within the terms of the trust deed. You could also keep some control by being a trustee yourself. This could be particularly relevant where one of your beneficiaries has special needs, as it can be designed to protect their long-term interests.
You might also like to consider benefiting charities close to your heart.
4. How do you want to transfer your wealth?
By following steps one to three, the ‘How?’ may well become clear. Timing plays a big part in this decision, as well as considerations around whether you can really afford to gift during your lifetime. If you can, you then need to decide whether to make absolute transfers or create a trust structure which, while adding complexity, may be the most effective way to achieve your objectives.
Talk to a wealth succession planning expert
Above all, it’s vital to start having conversations about the future with your loved ones. It’s also important to get the right balance between having enough capital and income to enjoy now, while passing on wealth to your family efficiently if you wish to do so.
Our wealth planning experts specialise in family succession planning and can advise all generations of your family, creating a joined-up approach that benefits everyone, working with existing legal or tax advisers where appropriate.
Need more help?
Whatever your needs, we can help by putting you in contact with the best expert to suit you.
Frequently asked questions about family wealth succession planning
It can be helpful to consider formalising a succession plan when you have significant wealth, property, investments, business interests or more complex family circumstances to consider. It is often best to start before a major life event prompts the conversation, so you have time to agree your priorities, update your Will, consider lifetime gifting and understand how much you may be able to pass on without compromising your own financial security.
Ownership and control do not always need to pass to the next generation at the same time. You may choose to transfer wealth gradually through lifetime gifts, trusts or family investment structures, while retaining an appropriate level of oversight. The approach you take will depend on your family circumstances, tax position, the age and financial experience of your beneficiaries and whether you need continued access to your income or capital.
It is important to review your succession plan regularly and whenever family, financial or legal circumstances change. This could include marriage, divorce, the birth of a child or grandchild, bereavement, a significant change in the value of your assets, the sale of a business, changes to tax rules, a move to another country or a beneficiary needing additional support. Reviewing your plan every two to three years can help you check it still reflects your wishes.
Fair does not always have to mean equal. One child may need support sooner, another may be involved in a family business, or a beneficiary may need additional protection. A well-considered family succession plan could use a combination of lifetime gifts, trusts and clear communication to balance fairness with your own long-term needs. Cashflow planning can also help show what you may be able to afford to give away while preserving enough wealth for later life, potential care costs and unexpected events.
As wealth passes between generations, investment portfolios may need to change to reflect changing time horizons, income needs, tax considerations and attitudes to risk. For example, a portfolio designed to provide retirement income may not be suitable for younger beneficiaries investing over a longer period, while inherited wealth may need to be managed alongside pensions, property or business assets. Regular reviews can help ensure the portfolio remains aligned to the needs and objectives of those involved.
Your succession plan may need to change if your family becomes more blended, international or financially complex. Second marriages, stepchildren, unmarried partners, vulnerable beneficiaries, family disagreements and assets held in different countries can all affect how you choose to pass on your wealth. Regularly reviewing your Will, trusts, beneficiary nominations and investment arrangements can help reduce uncertainty and keep your plan aligned with the people and causes that matter most to you.


